Charter PointFinance

Who we help

High-Performing Professionals

Medical professionals, engineers, accountants, lawyers, architects, and software & cybersecurity professionals. Different careers, one shared need: finance that understands how you work.

Surgeon at work in an operating theatre

01 / Your profession

Medical Professionals

Interns, registrars, consultants, specialists, locum doctors and practice owners.

Why specialist support matters

Rosters, overtime, on-call income, locum contracts and private billings can make a strong application look complicated. We put those details in context and compare lenders that understand your career pathway.

Benefits to explore

  • Potential LMI savings

    Eligible practising medical professionals may qualify for a lenders mortgage insurance (LMI) waiver at selected lenders. Accepted occupations, registration requirements and borrowing limits differ; not every medical role qualifies.

  • More of your income understood

    We help document salary, regular allowances, locum work and private billings so lenders can assess the full picture under their income policies. Not every lender accepts every income component.

  • From first home to practice ownership

    Compare home and investment loans alongside finance for practice purchases, premises, fit-outs and eligible diagnostic equipment, subject to separate business lending criteria.

Professional waivers require an eligible practising role and current registration accepted by the lender. A degree or job title alone is not enough.

Engineers reviewing site plans together

02 / Your profession

Engineers

Graduate and chartered engineers, project contractors, FIFO professionals and firm owners.

Why specialist support matters

Project contracts, day rates, FIFO rosters and allowances do not always fit a standard salary template. We help present contract history and cashflow clearly, with lending options that fit your next project or career move.

Benefits to explore

  • Specialist low-deposit options

    Selected specialist products accept engineers and offer lender-paid LMI for eligible owner-occupied purchases. This is different from a bank waiving LMI: compare the interest rate, fees and repayment structure, not just the upfront saving.

  • Contract and allowance income in context

    We bring together your employment history, current contracts and evidence of recurring allowances. How much a lender accepts depends on stability, documentation and its policy.

  • Finance beyond your home

    Explore investment lending, firm purchases, business premises and eligible vehicles or equipment. Working-capital options can help bridge project payment timing, subject to credit assessment.

Granite's published professional product includes university-educated engineers, three years in the same professional industry, eligible residency and a clear credit history. Property and credit criteria also apply; this is not a benefit offered by every lender.

Calculator, charts and accounting binders on a desk

03 / Your profession

Accountants

Practising CA, CPA and IPA members, employed accountants, partners and accounting practice owners.

Why specialist support matters

You spend your days looking after other people's finances. Your own lending may involve salary, partnership distributions or practice earnings. We help separate the details and compare policies that suit your qualifications and structure.

Benefits to explore

  • Up to 90% lending without LMI

    ANZ publishes an LMI premium waiver for eligible accountants borrowing up to 90% of the property's assessed value, with no minimum income for the waiver itself. A purchase still needs a deposit, stamp duty and other costs; normal affordability checks apply.

  • Membership can open more options

    NAB lists practising CA ANZ, CPA and IPA members for professional LMI eligibility. Accepted bodies vary by bank, so we check your current membership against each lender rather than assuming every accountant qualifies.

  • Support for partnership and practice plans

    We help present partnership distributions and business earnings for lender assessment, and compare finance for practice acquisitions, partner buy-ins, office premises and working capital.

Current membership of a lender-approved accounting body is required. ANZ's no-minimum-income waiver does not remove serviceability requirements. Loan, property and membership restrictions vary by lender.

Legal reference books stacked on a desk

04 / Your profession

Lawyers

Practising solicitors, barristers, eligible legal professionals, partners and law firm owners.

Why specialist support matters

Salary, bonuses, partnership drawings and self-employed billings can each be treated differently by a lender. We help present your income and practising credentials clearly, whether you are buying a home or building your firm.

Benefits to explore

  • A smaller deposit without the LMI premium

    ANZ publishes an LMI premium waiver for eligible legal professionals at up to 90% of the property's assessed value, with no minimum income for the waiver itself. Deposit, purchase costs and standard affordability requirements still apply.

  • Practising credentials recognised

    NAB also lists practising legal professionals with a current certificate from an accepted legal body. We compare your credentials with lender criteria; admission or a law degree alone does not establish eligibility.

  • Home and firm lending considered together

    Explore home and investment loans alongside partner buy-ins, firm acquisitions, office premises and working capital. Variable billings and distributions need supporting evidence and lender approval.

An eligible practising role and current practising certificate accepted by the lender are required. Loan and property limits apply. A professional waiver is not automatic credit approval.

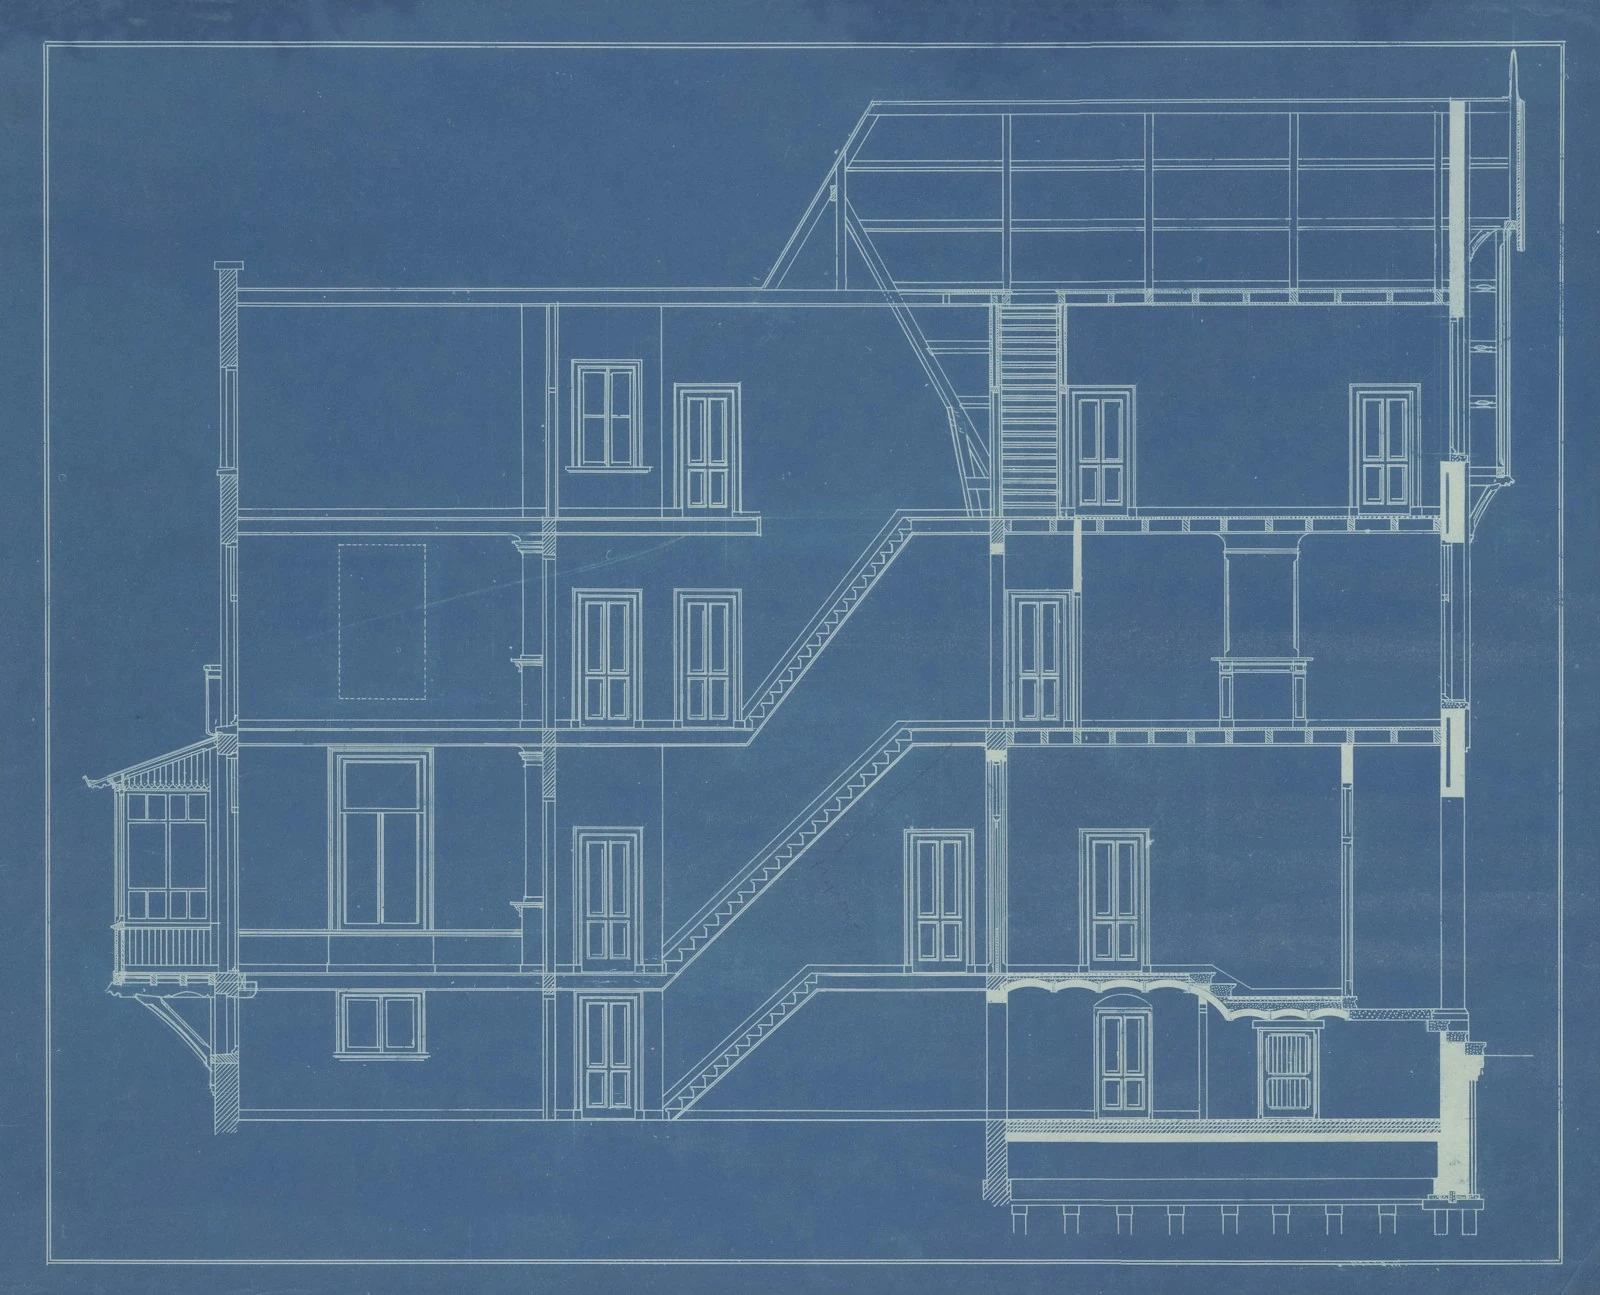
Architectural blueprint showing building elevations

05 / Your profession

Architects

Employed and registered architects, project consultants, partners and architectural studio owners.

Why specialist support matters

Design fees arrive in stages, projects run over long timelines and a studio's accounts may not reflect a simple monthly salary. We help make your income and commitments clear without assuming your profession guarantees a lender discount.

Benefits to explore

  • A clearer case for project-based income

    We help present salary, contract history, business accounts and staged project fees so lenders can assess your income under their policies. The benefit is a better-documented application, not a promise that all future fees will count.

  • Working capital for payment gaps

    Business loans, overdrafts or eligible invoice-finance options may help bridge the gap between doing the work and being paid. Availability depends on the business, invoice eligibility, security and lending criteria; costs and risks need comparison.

  • Room to grow your studio

    Compare finance for studio premises, fit-outs and eligible business equipment while considering your home and investment goals. These are general lending options, not architect-only entitlements.

Architects are not named in the ANZ and NAB professional LMI policies reviewed here. We do not promise an architect-specific waiver or rate discount; any exception must be confirmed with the individual lender.

Cybersecurity professional working at multiple computer screens

06 / Your profession

Software & Cybersecurity

Software developers and engineers, cybersecurity specialists, IT contractors, consultants and technology business owners.

Why specialist support matters

Day-rate contracts, changing projects, bonuses and consulting revenue can make your income more complex than a regular salary. We help present your employment history and business accounts clearly, so your finance reflects how you actually work.

Benefits to explore

  • Specialist options for IT professionals

    Granite's published professional product includes IT professionals, with industry certifications accepted instead of a university degree. Eligible owner-occupied borrowers may access lender-paid LMI rather than paying an upfront premium. This is not a bank LMI waiver; compare the interest rate, fees and accelerated repayment structure.

  • Contract and business income, understood

    We help document contracts, recurring client revenue and business financials for lender assessment. NAB publishes a pathway to consider a single year's financial statements for eligible self-employed borrowers at up to 80% loan-to-value ratio, subject to other criteria. Future contracts and every income component are not automatically accepted.

  • Finance for your next stage

    Compare home and investment lending alongside business premises, working capital and eligible technology equipment. These are general lending options, not software- or cybersecurity-only entitlements; equipment eligibility, security and affordability need individual assessment.

Granite requires three years in the same professional industry, a university degree or accepted IT industry certifications, eligible residency and a clear credit history. Your software or cybersecurity role must be confirmed as eligible by the lender. No blanket profession-based bank LMI waiver or rate discount is promised.

A benefit is not a guarantee

LMI protects the lender, not the borrower. Waivers and lender-paid LMI can reduce upfront costs but do not guarantee a lower overall loan cost. Lender policies, professional memberships, income requirements, loan limits and property criteria vary and can change. All lending is subject to credit approval. Sources reviewed 14 October 2026; Adam will confirm current eligibility for your circumstances.

Success starts with understanding

The following are illustrative scenarios, not verified client success stories.

Illustrative scenario · Medical

A registrar planning a first home

Base salary is only part of the picture. A careful review of regular overtime, on-call and penalty income can help a lender assess the full application rather than treating it as an ordinary salary.

Illustrative scenario · Engineering

A contractor ready for the next step

A day-rate contractor with a new project needs their income explained clearly. Contract history, current terms and cashflow can be brought together to support a home or business finance application.